
Do I Need a Home Appraisal to Remove PMI?
In most cases, yes. If you want to remove PMI early because your home has gone up in value, you’ll need an appraisal to prove it. Your loan servicer sets the rules and often orders or approves the appraisal, so call them first. If your home has gained value, an appraisal can help you drop PMI years ahead of schedule.
Removing PMI (private mortgage insurance) is one of the easiest ways to lower your monthly mortgage payment. Here’s how it works for homeowners across North Carolina.
When Does PMI Go Away on Its Own?
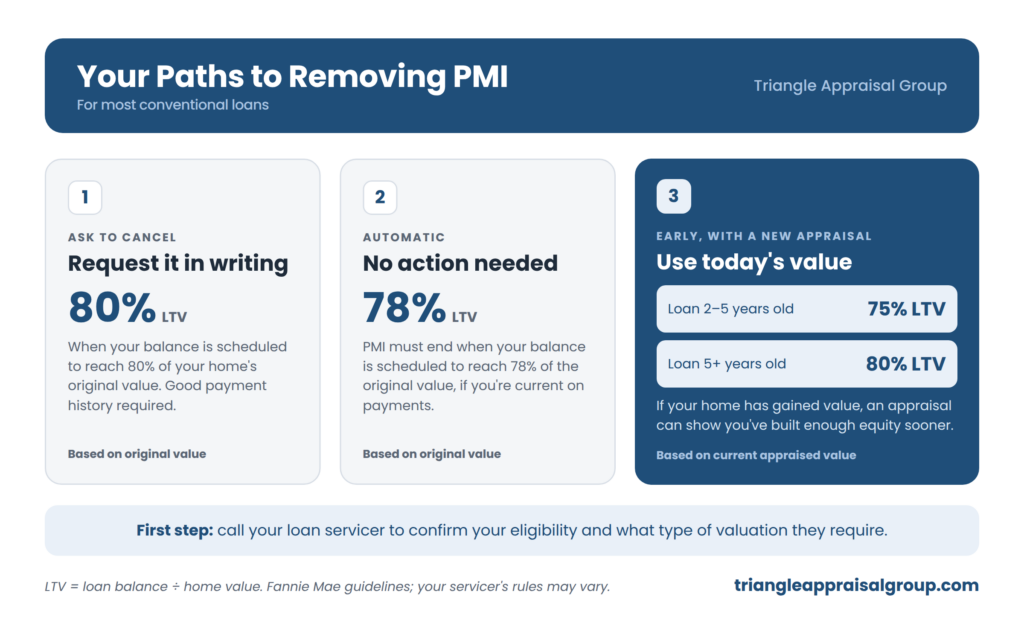
Federal law gives you two built-in ways out of PMI on a conventional loan, based on your home’s original value (usually the purchase price):
At 80%: You can ask your servicer in writing to cancel PMI once your balance is scheduled to reach 80% of the original value. You’ll need a good payment history, and your servicer may ask for an appraisal to show the value hasn’t dropped.
At 78%: PMI must end automatically once your balance is scheduled to reach 78%, as long as you’re current on payments.
That can take years. If your home’s value has gone up, a new appraisal may get you there much sooner. (CFPB)
How Much Equity Do You Need to Remove PMI?
When you ask to remove PMI based on your home’s current value, the rules depend on how long you’ve had your loan. For most conventional loans backed by Fannie Mae:
How long you’ve had the loan
Equity you need
Loan-to-value (LTV)
Less than 2 years
Usually not eligible
—
2-5 years
25%
75% or less
More than 5 years
20%
80% or less
*If you’ve made major improvements, like an addition or a full remodel, your servicer may waive the 2-year wait. You’ll still need 20% equity.
TAG Tip: Before you request PMI removal, check your payment history. Most servicers require no payments 30 or more days late in the past year, and none 60 or more days late in the past two years. A clean record keeps the process moving.
Here’s how to estimate your equity:
- Home appraises for $400,000
- Loan balance: $310,000
- Equity: $400,000 − $310,000 = $90,000
- Equity percentage: $90,000 ÷ $400,000 = 22.5% (77.5% LTV)
In this example, a homeowner who’s had the loan more than 5 years could remove PMI. Someone at 3 years would need about $10,000 more in equity to reach 25%.
Who Orders the Appraisal?
Start with a call to your loan servicer. Ask them:
- Am I eligible to remove PMI based on my home’s current value?
- What type of valuation do you require, and do you order it or do I?
- Do you have a list of approved appraisers?
Many servicers order the appraisal themselves, or require an appraiser from their approved list. For most Fannie Mae loans, the valuation must include an inspection of both the inside and outside of the home.
TAG Tip: A private appraisal can still be a smart first step. It gives you a clear picture of your home’s value before you start the process, so you know whether you’re close, and it helps you avoid paying for a servicer appraisal that comes in short.
Appraisal vs. BPO vs. AVM
Your servicer may use one of these to check your home’s value:
Appraisal: A licensed appraiser inspects the home and analyzes comparable sales. It’s the most thorough option.
BPO (broker price opinion): A real estate agent’s estimate of what the home would sell for. It’s quicker, but less detailed.
AVM (automated valuation model): A computer estimate based on public data, like a Zestimate.
AVMs are quick and low-cost, but they often miss key details like:
- Recent renovations
- The home’s current condition
- Expert local market insight
A full appraisal includes an in-person inspection and a careful look at comparable sales, done by a real person, not a computer. That difference can show equity an algorithm misses.
Do I Have to Refinance to Remove PMI?
Not necessarily. But refinancing may be worth it if:
- Your current interest rate is high: A refinance can remove PMI and lower your rate, saving you more overall.
- You plan to stay in your home for several years: That gives you time to make up the closing costs through lower payments.
Refinancing? Learn how a refinance appraisal differs from a purchase appraisal.
What About FHA Loans?
FHA loans have MIP (mortgage insurance premium), not PMI, and the rules are different. For most FHA loans made after June 2013, MIP lasts for the life of the loan if you put down less than 10%, or 11 years if you put down 10% or more. An appraisal alone won’t remove it. The usual way out is refinancing into a conventional loan once you have enough equity.
Why Paying for an Appraisal Now Can Save You Money Later
Before you start the PMI removal process, ordering a private appraisal can help you:
- Confirm whether you’ve reached the equity you need
- Avoid unnecessary back-and-forth with your servicer
- Know exactly where you stand before you apply
PMI often runs $100–$300+ per month (Freddie Mac), which means you could be paying $1,200–$3,600+ a year on top of your mortgage.
By comparison, a one-time private appraisal often costs less than two months of PMI. If it shows you’ve reached the equity you need, it can pay for itself quickly. Contact us for a quote.
Want a lower-cost first look? A desktop appraisal costs less than a full appraisal and is done by a certified appraiser using local market data and comparable sales, without an in-person visit. It’s a great planning tool to see if you’re close, but most servicers will require a full inspection before they remove PMI.
FAQs
Can I get my house appraised to remove PMI?
Yes. If your home has gained value, a new appraisal can show you’ve reached the equity you need. Call your servicer first, since many order the appraisal themselves or require an approved appraiser.
Will a high appraisal at purchase remove PMI?
No. When you buy, your loan is based on the lower of the price or the appraised value, so a high appraisal won’t remove PMI at closing. Learn more in Appraisal Higher Than Purchase Price.
Can my servicer use a BPO instead of an appraisal?
Some servicers accept a broker price opinion, but many require a full appraisal with an interior and exterior inspection. Ask your servicer what they accept before ordering anything.
Do home improvements help me remove PMI sooner?
They can. Major improvements may raise your home’s value, and some servicers will waive the 2-year waiting period if you’ve made substantial upgrades. See What Renovations Really Impact a House Appraisal.
Does PMI ever come off automatically?
Yes. On conventional loans, PMI must end once your balance is scheduled to reach 78% of the original value, as long as you’re current on payments.
Ready to see if you can drop PMI? Learn about our PMI Removal Appraisals or contact the TAG team. Reports are finalized 3–5 business days after inspection.
Connect with Rachel Mann on LinkedIn:
Thanks for reading! We love sharing insights from the TAG team, and we’re always looking to connect with others who are passionate about real estate, marketing, and community.
Have thoughts to share or want to collaborate on a future post? Let’s talk!